
Running a small business often means making decisions with limited resources. You may have a strong idea, loyal customers, and a clear growth plan, but access to enough capital can still determine how quickly you can move forward.
Small business funding can help cover everything from startup costs and inventory to equipment purchases, hiring, marketing, and unexpected expenses. However, funding isn’t one-size-fits-all. A short-term cash-flow problem may require a very different solution from a major expansion.
This guide explains the main financing options available, how to choose between them, what lenders typically look for, and how to prepare a stronger application.
What Is Small Business Funding?
Small business funding refers to the capital a business obtains to cover expenses, maintain operations, or support growth.
Depending on the situation, funding may come from a bank, online lender, government program, investor, crowdfunding platform, or the business owner’s personal resources.
Businesses commonly use funding for:
- Starting a new business
- Purchasing equipment
- Buying inventory
- Managing payroll and operating expenses
- Expanding into a new location
- Hiring employees
- Launching marketing campaigns
- Improving technology
- Managing temporary cash-flow shortages
The important point is that funding should solve a specific business need rather than simply provide extra money.
Why Do Small Businesses Need Funding?
Even profitable businesses can experience periods when expenses arrive before revenue does. For example, a retailer might need to purchase seasonal inventory months before making most of its sales.
Funding can provide working capital that helps bridge these gaps.
Startup Costs
New businesses often need capital before they generate consistent revenue. Costs can include equipment, licenses, rent, website development, initial inventory, insurance, and marketing.
Working Capital
Working capital helps businesses pay regular expenses such as wages, rent, utilities, suppliers, and other operating costs.
Business Expansion
A growing company may need additional money to hire staff, purchase equipment, increase inventory, or open another location.
Unexpected Expenses
Repairs, supply disruptions, or sudden changes in customer demand can put pressure on cash reserves. Access to financing can provide a financial cushion when appropriate.
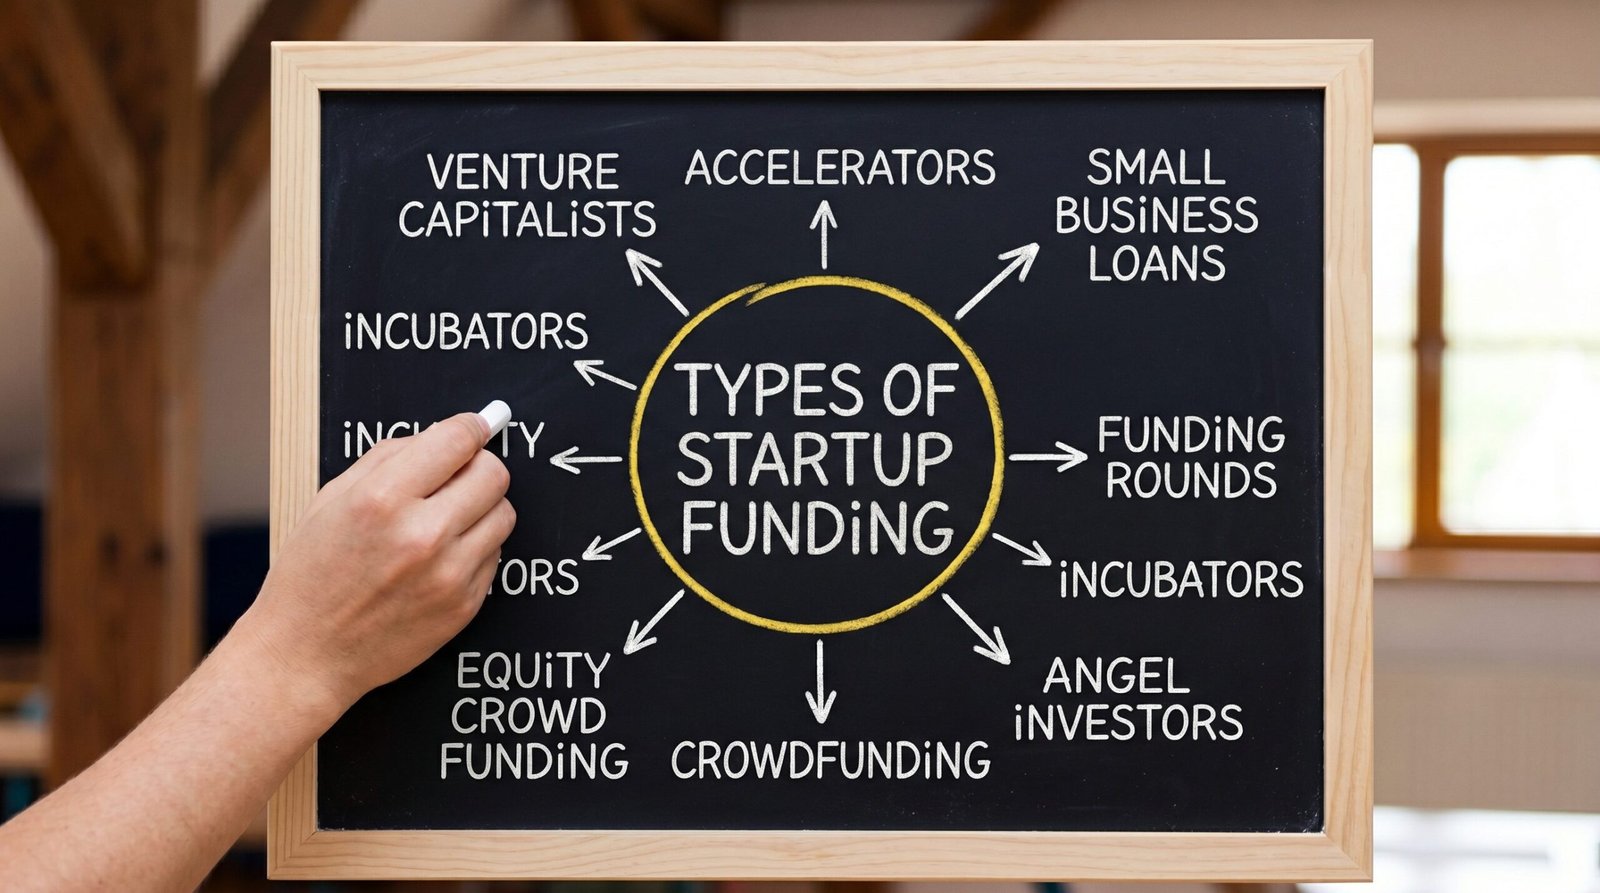
Types of Small Business Funding
There are several ways to finance a business. Each option has different requirements, costs, risks, and repayment structures.
| Funding Type | Best For | Repayment Required? |
| Business Term Loan | Large planned expenses | Yes |
| Business Line of Credit | Flexible working capital | Usually |
| Equipment Financing | Purchasing equipment | Yes |
| SBA-Backed Loan | Eligible U.S. businesses | Yes |
| Business Grant | Specific eligible purposes | Usually no |
| Crowdfunding | Products and community-backed ideas | Depends |
| Angel/Investor Funding | High-growth businesses | Usually no loan repayment |
| Business Credit Card | Smaller short-term expenses | Yes |
| Personal Savings | Early-stage or small expenses | No |
Business Term Loans
A term loan provides a lump sum that you repay over an agreed period, usually with interest.
This can work well when you know exactly how much you need and what you’ll use the money for. For example, a business purchasing a commercial vehicle or renovating a store may prefer predictable loan payments.
Before accepting a loan, compare the total repayment cost rather than looking only at the monthly payment.
Business Lines of Credit
A business line of credit gives you access to a predetermined amount of money. You generally pay interest on the amount you actually draw, depending on the agreement.
This can be useful for recurring expenses or fluctuating cash-flow needs.
For example, a business with seasonal revenue could use a line of credit during slower months and repay the balance when sales increase.
Equipment Financing
Equipment financing is designed specifically for purchasing business equipment. The equipment itself may serve as collateral, depending on the financing arrangement.
It’s commonly considered for machinery, commercial vehicles, computers, restaurant equipment, and other business assets.
Grants
Business grants can be attractive because they generally don’t require repayment when the recipient meets the program’s conditions.
However, grants are often competitive and may be restricted to particular industries, locations, business activities, or groups. Never assume a grant is guaranteed simply because your business meets the basic eligibility criteria.
Crowdfunding
Crowdfunding allows businesses to raise money from a large number of people, often through an online platform.
Reward-based crowdfunding may involve offering a product or benefit to supporters. Equity crowdfunding can involve giving investors an ownership interest, subject to applicable laws and platform rules.
Crowdfunding can also help validate whether customers are genuinely interested in a product.
Investor Funding
Angel investors and venture capital firms may provide capital in exchange for equity or another ownership-related arrangement.
This approach can be useful for businesses with significant growth potential. However, bringing in investors means giving up some control or ownership, so the long-term implications should be considered carefully.
How to Choose the Right Funding Option
The best funding source depends on your circumstances rather than simply the amount you can qualify for.
Start by answering these questions:
- How much do I actually need?
- What will the money be used for?
- How quickly do I need it?
- Can the business comfortably make repayments?
- How much will the financing cost in total?
- Does the agreement require collateral or a personal guarantee?
- Will taking the funding affect ownership or control?
For example, borrowing a large amount for a small temporary cash-flow gap could create unnecessary costs. Likewise, using a short-term financing product to pay for a long-term investment may put pressure on cash flow.
What Lenders Look For
Lenders typically assess whether a business has a reasonable ability to repay what it borrows. Exact requirements vary by lender and financing product.
Common factors include:
Credit History
Personal and business credit histories may be reviewed. Stronger credit can improve eligibility and, in some cases, financing terms.
Revenue and Cash Flow
Established lenders may want evidence that the business generates enough revenue and cash flow to support repayments.
Time in Business
A business with several years of operating history may have more financial records available than a newly established company.
Business Plan
A clear business plan can help explain how the funding will be used and how the business expects to generate returns.
Financial Documents
Depending on the application, you may need documents such as:
- Bank statements
- Tax returns
- Profit and loss statements
- Balance sheets
- Revenue records
- Business registration documents
- Outstanding debt information
How to Apply for Business Funding
A well-prepared application can make the process easier.
1. Define the Purpose
Write down exactly why you need the money. “Business growth” is less useful than a specific plan such as purchasing $20,000 of equipment or financing additional inventory.
2. Calculate the Required Amount
Avoid borrowing more than necessary. Estimate the actual cost and include a reasonable buffer only when justified.
3. Review Your Finances
Check your revenue, expenses, existing debts, credit profile, and cash flow.
4. Compare Providers
Don’t focus solely on the advertised interest rate. Review fees, repayment terms, collateral requirements, penalties, and the total cost of financing.
5. Prepare Your Documents
Having financial statements and other required documents ready can reduce delays.
6. Read the Agreement Carefully
Before signing, make sure you understand the repayment schedule, fees, interest calculation, guarantees, and consequences of missed payments.
Common Funding Mistakes to Avoid
Getting access to capital doesn’t automatically mean it’s a good deal.
Avoid these common mistakes:
- Borrowing more than the business can comfortably repay
- Choosing funding based only on the monthly payment
- Ignoring fees and the total financing cost
- Using long-term financing for short-lived expenses without a clear reason
- Failing to compare multiple options
- Signing an agreement without understanding the terms
- Mixing personal and business finances
- Assuming approval is guaranteed
- Using borrowed money without a measurable business purpose
A simple cash-flow forecast can help you determine whether projected income is sufficient to handle new obligations.
Key Takeaways
- Small business funding can support startup costs, working capital, expansion, equipment, and unexpected expenses.
- Business loans and lines of credit are common financing choices, but they’re not the only options.
- Grants can provide non-repayable funding when a business meets specific requirements.
- Investors may provide capital without traditional loan repayments, but they can receive ownership in return.
- Compare the total cost, not just the interest rate or monthly payment.
- Borrow according to your business’s realistic repayment capacity.
- Prepare financial records before applying.
- Always read funding agreements carefully before accepting the money.
FAQs
1. What is the best small business funding option?
There isn’t one option that’s best for every business. A term loan may suit a major planned purchase, while a line of credit may be more appropriate for short-term working capital. The right choice depends on your funding purpose, financial position, eligibility, and repayment capacity.
2. Can a new business get funding?
Yes, new businesses can have funding options, although they may face stricter requirements because they have limited operating and financial history. Depending on the country and circumstances, entrepreneurs may consider personal savings, certain loans, grants, crowdfunding, or investment.
3. Does business funding always require collateral?
No. Some financing products may be unsecured, while others require business assets, personal guarantees, or other forms of security. Requirements vary significantly between lenders and products.
4. How much business funding should I borrow?
Borrow enough to accomplish the specific goal without creating unnecessary repayment pressure. Start with a detailed cost estimate and compare it with your expected cash flow.
5. Can I use business funding for working capital?
Yes. Many businesses use financing for working capital, including inventory, payroll, supplier payments, rent, and other operating expenses. However, make sure the repayment structure matches the timing of your business’s cash flow.
6. What documents are needed for business funding?
Requirements vary, but lenders may request financial statements, bank statements, tax records, business registration details, revenue information, identification, and details about existing debts.
7. Is grant funding better than a business loan?
Grants can be attractive because eligible recipients generally don’t repay the grant. However, grants can be highly competitive and restricted to specific purposes. A loan may be more accessible when a business needs funding for a broader purpose and can manage the repayments.
Conclusion
Finding the right small business funding starts with understanding what your business actually needs. Whether you’re launching a company, managing working capital, purchasing equipment, or preparing for expansion, different financing options have different advantages and risks.
Take time to calculate the required amount, review your cash flow, compare providers, and understand the complete cost before committing. Good financing should support your business strategy—not create a repayment burden that limits future growth.
When funding is chosen carefully and used for a clear purpose, it can become a practical tool for building a stronger and more sustainable business.
Learn About: Business News
